Build an approval‑ready credit profile
Understand what’s driving your credit decisions, identify items that may be unfair or inaccurate, and take a structured next step toward stronger approvals and better terms.
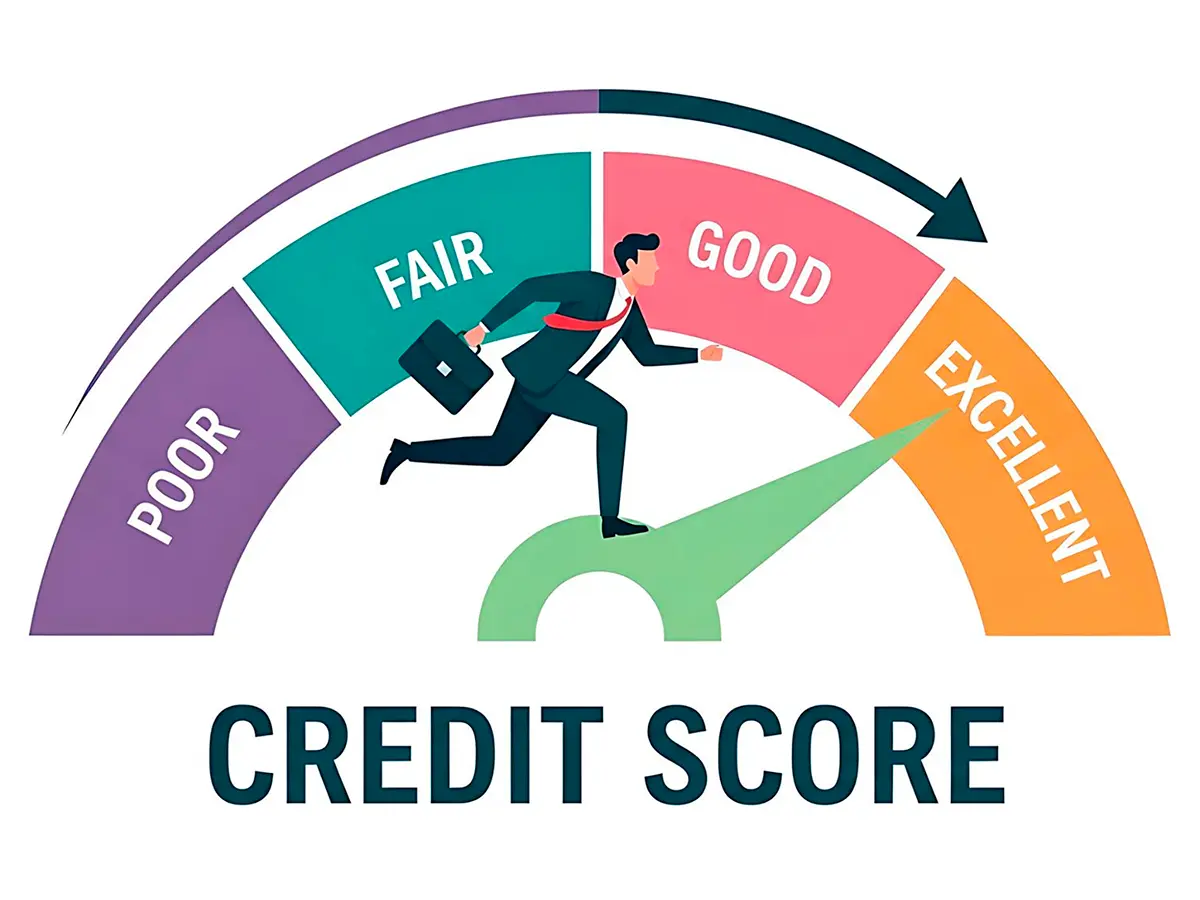
Built around established U.S. credit reporting practices and dispute procedures under the Fair Credit Reporting Act (FCRA). No unrealistic promises—just clarity, documentation, and structured credit improvement.
Unlock more options
Choose the outcome you care about. We’ll outline what improves it—and what to watch for—so you can move forward with confidence.
Your path to stronger credit
A stronger credit profile can mean better approval odds, improved loan terms, and more financial flexibility. Get a clear, no-fluff overview of what credit improvement can help you achieve — then take the next step when you're ready.
Credit decisions in the U.S. are typically influenced by payment history, utilization ratios, account age, recent inquiries, and the accuracy of reporting across major credit bureaus.
Even small inconsistencies can affect lending algorithms. A structured credit improvement approach focuses on verified data, responsible usage patterns, and consistent financial behavior.
*Results vary. This page does not guarantee outcomes.
How it works
A straightforward workflow used by reputable credit‑support programs: review, challenge what’s questionable, and build stronger habits while updates are processed.
Review your starting point
Clarify your goal and look at what’s currently affecting approvals and terms.
Identify what can be challenged
See what information is typically needed, what to expect next, and how the workflow usually looks.
Move forward
Continue to explore available options and take the next step toward better credit outcomes.
credit repair colorado springs: a no-nonsense comparison
What to expect before you start
Credit repair is mostly documentation, timing, and persistence. Disputes move in 30 - 45 day cycles with the bureaus, and three to six cycles is common for a full file review. Clear errors (mixed files, duplicate collections, wrong balances, identity-theft accounts) are the most fixable; accurate late payments and charge-offs rarely come off without a verified mistake. Medical collections under $500 have been removed by the major bureaus, and paid medical collections no longer report, which helps locals with hospital balances. You can pull reports free at AnnualCreditReport.com and monitor weekly. Realistic check: paying a collection doesn't erase its history; it just updates to paid, which is still better for underwriting than unpaid. No one can guarantee deletions, and any promise of "overnight 750+" is sales talk, not process.
Colorado Springs factors that shape results
Military moves and new leases push timelines; property managers along Powers and in Old Colorado City often screen fast, and mortgage lenders still use older FICO versions (2/4/5) that weigh collections differently than app scores. On a windy afternoon downtown, I watched a server on Tejon Street pull up a credit app after a landlord asked for her mid-score; the immediate win wasn't a deletion - it was correcting a wrong address and disputing a duplicated collection to stop a denial. Expect similar small, verifiable steps to add up.
Compare your options
DIY disputes
- Best when you have clear documentation and time to mail targeted letters.
- Use precise claims: wrong dates, balance mismatches, or accounts that aren't yours beat generic templates.
- File police/FTC reports for identity theft; ask furnishers for method-of-verification.
Nonprofit counseling (HUD-approved/housing + DMP)
- Focuses on budgeting and creditor concessions, not deletions.
- Debt Management Plans can lower APRs and stabilize utilization - often more score impact than a single deletion.
- Good for mortgage prep and transparent timelines.
Local firms
- Pros: face-to-face expectations, city-specific knowledge (lease underwriting, PCS timing).
- Look for itemized dispute strategies and monthly status calls.
- By law, contracts and disclosures are required; no advance fees before work is performed.
National platforms
- Pros: portals, scale, predictable pricing.
- Cons: generic letters can trigger stall responses; less nuance with Colorado creditors and medical providers.
- Ensure they tailor disputes and don't shotgun the same wording to every bureau.
Costs and timelines
DIY: postage and notary, usually under $50 total. Counseling: often free intake, modest monthly if on a DMP. Local or national repair: commonly $70 - $150/month or pay-per-deletion. Beware paying large upfront "analysis" fees. One to three months for easy fixes; six to nine months for layered issues. Time-barred debts in Colorado are generally six years, but they can still be reported up to seven years; don't restart clocks by making small test payments without a plan.
Transparency checklist
- What evidence will you use per account?
- How many items will you dispute per cycle, and why?
- How do you handle furnisher reinsertions?
- What happens if results stall after two cycles?
- How will progress be measured beyond a single score?
- What exact fees occur and when?
Realistic outcomes
Deleting one verified collection can swing 20 - 80 points, or barely move a mortgage score; utilization cuts, late-fee reversals, and removing duplicates often add steadier gains. For homebuyers here, target mid-score thresholds (620, 660, 680+) with a mix of deletions, utilization management, and on-time history. Whether you choose DIY, counseling, a local pro, or a national platform, make transparency your filter: clear evidence, measured expectations, and repeatable steps. That's how credit repair in Colorado Springs stops being mystery and starts looking like process.
With White, Jacobs and Associates, you'll get the only Colorado Springs credit repair that matters. Our express services and aggressive methods get real results ...
Top 10 Best Credit Repair in Colorado Springs, CO - February 2025 - Yelp - Pikes Peak Credit Repair, Give Yourself Credit, Superior Credit Repair, ...
The Phenix Group credit repair company can help restore your credit scores in the shortest possible time, so you can secure your business financing. TPG, a ...
Frequently asked questions
A clear next step — without the guesswork
See what’s impacting approvals and what may deserve a closer look.
Understand how disputes are structured and what documentation matters.
Improve utilization, consistency, and long-term credit stability.
See what improving your credit could change
Take a structured next step based on your current profile — and decide with clarity.